Three digits. That’s all a credit score is, yet it quietly shapes whether you get a loan, what interest rate you pay, and sometimes whether a landlord says yes. Many people only discover their score the day a loan gets rejected, which is the worst possible time to learn about it.
Let’s take the mystery out of it. Here’s what CIBIL score ranges mean in 2026, what counts as “good”, and what you can realistically do to improve yours.
What is a CIBIL score?
CIBIL, now part of TransUnion CIBIL, is one of India’s credit bureaus. It collects data on how you’ve handled loans and credit cards, and turns it into a three-digit score between 300 and 900. Other bureaus such as Experian, Equifax and CRIF High Mark use similar scales, so your scores may differ slightly between them, but the logic is the same.
The score is a summary of your credit behaviour. A higher number tells lenders you’re likely to repay on time. A lower number tells them to be careful.
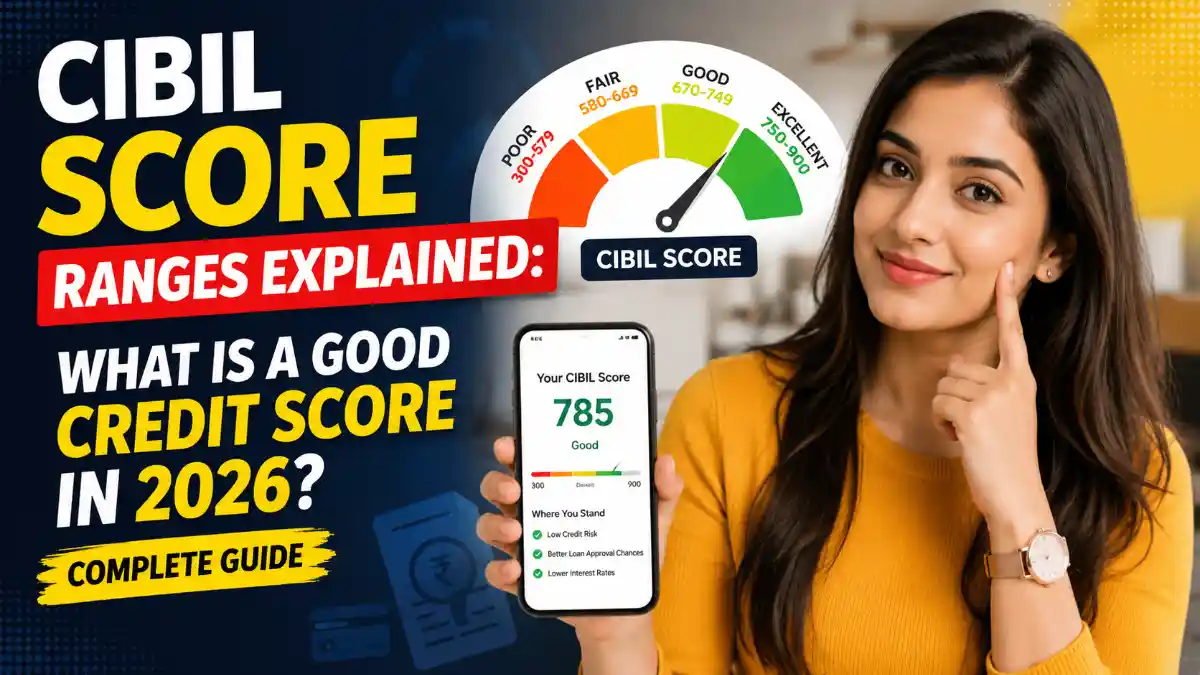
CIBIL score ranges
- 300 to 549: Poor. Lenders see high risk. Approval is difficult and rates are expensive if approved.
- 550 to 649: Fair. Some lenders may approve you, usually with stricter terms.
- 650 to 749: Good. Most lenders will consider you, though the best rates may stay out of reach.
- 750 to 900: Excellent. Easier approvals, higher limits and better interest rates.
These bands are a general guide and each lender sets its own cut-offs. As a rough rule, 750 and above is the sweet spot most banks look for on personal loans and home loans.
There’s also “NA” or “NH”, which means no credit history. It isn’t bad, just empty. Everyone starts there.
What affects your score
Payment history (the biggest factor)
Do you pay EMIs and credit card bills on time? Even a few late payments can drag your score down, and serious delays like 90 days overdue hurt a lot more.
Credit utilisation
This is the share of your credit limit that you’re using. If your card limit is Rs 1 lakh and you spend Rs 70,000 each month, utilisation is 70 percent, which looks risky. Keeping it under 30 percent is a widely used guideline.
Length of credit history
Longer histories help. Your oldest account matters, which is why closing an old card can sometimes lower your score.
Credit mix
A healthy mix of secured loans (like home or car loans) and unsecured credit (like cards and personal loans) shows you can handle different types. Don’t take loans just to improve this though.
Recent enquiries
Each time you apply for a loan or card, the lender checks your report. Many applications in a short period suggest desperation for credit, and can lower your score temporarily.
Why it matters
- Loan approval. Banks often reject applications below 700.
- Interest rate. A higher score can mean a noticeably lower rate. On a large home loan, even half a percent is lakhs saved over the term.
- Credit card eligibility and limits. Better score, better cards.
- Negotiating power. With an excellent score you can ask for fee waivers and lower rates.
- Other situations. Some employers in the financial sector and some landlords check credit reports as well.
See how rates differ in our guide to personal loan interest rates.
How to check your score
You’re entitled to one free credit report per year from each credit bureau in India. You can get it from the bureau’s official website after verifying your identity with PAN and other details. Many banks and apps also show your score for free. Checking your own score is a soft enquiry and doesn’t lower it.
When you view your report, read it line by line. Look for accounts you don’t recognise, wrong payment statuses, or loans you’ve already closed that still show as active. Errors are more common than you’d think.
Fixing mistakes on your report
If you find an error, raise a dispute on the bureau’s website with supporting documents such as a closure letter or payment proof. The bureau contacts the lender, who must verify and respond. The process can take 30 days or so, so start early before applying for a major loan.
Realistic expectations
A score doesn’t jump overnight. Clearing a long overdue account or lowering utilisation can show results in one to three months. Rebuilding from poor to good often takes a year or more of clean behaviour. Be wary of anyone who promises to “repair” your score for a fee in a week. There are no shortcuts, and some of these services are scams.
For practical steps, read how to increase your CIBIL score.
Common myths
- “Checking my score lowers it.” Not true for your own checks.
- “Income affects my score.” Income isn’t part of the score. It matters for loan eligibility, but not for the number itself.
- “I should keep a balance on my card to build credit.” No. Pay in full. You don’t need to pay interest to build a score.
- “Closing a card improves my score.” It can reduce your available credit and shorten your history, which can hurt.
- “Having no loans means a great score.” It means no score. Lenders can’t judge you without history.
A look at what lenders see
When a bank pulls your credit report, the score is only the headline. The loan officer, or more often the bank’s automated system, also looks at the details underneath. They see how many accounts you have and how old they are, whether you’ve ever missed a payment and by how many days, how much of your card limit you use each month, and how many times other lenders have checked your report recently. Two people with the same score of 740 can look quite different on paper, one with ten years of tidy history and another with a thin file and one recent loan.
Banks also layer their own rules on top. A lender might approve a personal loan at 720 for a salaried employee at a large company but ask for 780 from a self-employed applicant. That’s why a rejection from one bank doesn’t mean you’ll be rejected everywhere. It also explains why asking for a “pre-approved” offer from your own bank is often smoother than applying cold elsewhere.
A practical habit: check your report once or twice a year even if you’re not planning to borrow. Catching a wrong entry early, long before you need a loan, gives you time to dispute it without pressure.
Frequently asked questions
What is a good CIBIL score for a home loan?
Most lenders prefer 750 or above, though some approve lower scores at higher rates.
How often does my score update?
Lenders typically report to bureaus monthly, so changes show up within 30 to 45 days.
Can I get a loan with a score of 650?
Possibly, but with a higher interest rate or lower amount. Some lenders will decline.
Does a settled loan affect my score?
Yes. “Settled” means you paid less than owed, and it appears negatively on your report for years. Closing a loan in full is much better.
Is a score of 900 necessary?
No. Anything above 750 to 800 is usually enough for the best offers.
This article is for general information and isn’t financial advice. Score ranges and lender criteria vary.